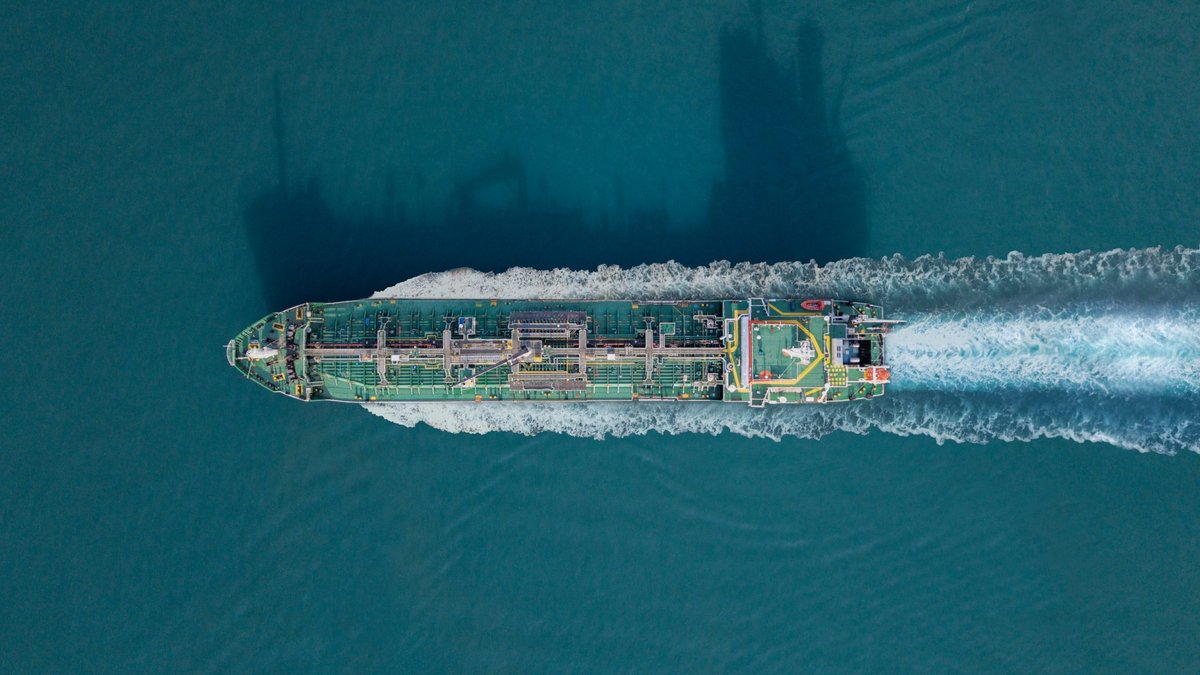
Global infrastructure mergers and acquisitions (M&A) activity has slowed in 2025, with deal values declining from $28 billion in 2024 to $22 billion, while completed transactions dropped from fifty-one to forty. Excluding Hutchison Ports’ proposed acquisition, the decline stems from wider economic uncertainty and tighter financing conditions. Despite this, investor demand for strategically important assets has remained stable.
Ports now critical for supply chains and security
Ports now occupy a distinct position among infrastructure assets. No longer viewed simply as transportation hubs, they function as essential nodes in global supply chains, energy security frameworks, and national defense strategies. Recent disruptions—including the COVID-19 pandemic, the Red Sea crisis, and renewed tensions in the Strait of Hormuz—have intensified focus on geographic diversification and operational resilience. While legal processes for M&A remain unchanged, geopolitical risks now fundamentally alter how deals are assessed, structured, and negotiated.
Ports serve dual purposes: they generate commercial revenue while also supporting trade, logistics, and security infrastructure. Their acquisition is rarely evaluated using only cash flow projections. Governments and regulatory bodies increasingly examine foreign investments in ports through the lens of broader public interests, creating additional hurdles for approvals and oversight. A port’s geographic location, connections to trade routes, and role in diversifying an investor’s network now influence valuation, often justifying premiums beyond traditional financial performance.
The United States demonstrates this evolving approach. The Committee on Foreign Investment in the United States (CFIUS) expanded its authority under the Foreign Investment Risk Review Modernization Act (FIRRMA) in 2018, covering minority stakes in critical infrastructure, technologies, and data systems. Even before FIRRMA, port transactions faced political scrutiny: Dubai Ports World’s 2006 bid for U.S. port operations triggered congressional opposition despite CFIUS approval. Today, national security considerations extend beyond competition policy to foreign investment reviews.
Investment approaches have adapted accordingly. In the early 2000s, port acquisitions centered on container volume and revenue growth. By the 2010s, operators broadened into inland logistics and supply chain integration. Currently, resilience drives decision-making. Investors may ask whether a trade corridor could be blocked, if sanctions risks are concentrated in one region, and how an acquisition balances their overall portfolio.
Legal frameworks adapt to geopolitical transaction risks
The legal tools, share purchase agreements, due diligence processes, and valuation methods, remain the same. However, their application has shifted. A buyer acquiring a port to enhance network resilience will prioritize governance rights, concession stability, and long-term regulatory certainty over short-term financial gains. Transactional lawyers now play an expanded role, aligning legal execution with commercial and geopolitical strategy.
Gulf-based port operators are leading this diversification trend. DP World’s reported interest in Associated British Ports in the U.K., its investments in Senegal and India, and AD Ports Group’s acquisition of MBS Logistics illustrate this pattern. These initiatives reduce concentration risk while opening access to new markets.
Valuation methods now incorporate this strategic shift. Buyers evaluate targets not only by cash flow projections but by how they strengthen portfolio resilience. A port in a different jurisdiction may command a premium for diversifying trade routes and lowering geopolitical exposure. Due diligence now extends beyond legal risks to assess how an acquisition integrates into the acquirer’s broader network.
Foreign investment screening introduces additional complexity. Regulators may increasingly examine infrastructure assets tied to supply chains or national security, which can be regardless of the investor’s risk profile. This affects transaction timelines, risk allocation, and contractual protections. Material adverse change (MAC) clauses, for example, may now address sanctions or route disruptions as material risks.
Deal structures evolve to split risk and gain approvals
Deal structuring has also adapted. Phased investments, joint ventures, and sovereign co-investments allow operators to diversify without overconcentrating risk. Gulf Cooperation Council (GCC) sovereign wealth funds are increasingly partnering with port operators, sharing capital exposure and easing foreign direct investment screening in target markets.
Operators employ varied approaches: some rely on internal cash flows for speed, while others leverage sovereign co-investors to expand deal capacity. The choice depends on financial strength, risk tolerance, and strategic priorities.
Strategic buyers now evaluate port acquisitions through two perspectives: traditional financial metrics and their contribution to portfolio resilience. While discounted cash flow models and comparable transaction analysis remain essential, acquirers increasingly weigh geopolitical diversification benefits. A port’s position along alternative trade corridors-such as the Suez Canal, Arctic routes, or Pacific Rim hubs-can justify a premium if it reduces dependence on a single maritime bottleneck. This shift appears in Gulf operators’ acquisitions of European and African ports, where the primary motivation is rerouting cargo away from high-risk zones rather than maximizing container throughput.
These provisions are frequently paired with representations and warranties that explicitly address sanctions exposure, political stability covenants, and pending national security reviews that could derail the deal. The post-closing indemnity period can also be extended to cover geopolitical events occurring within a specified timeframe after closing.

Leave a Reply