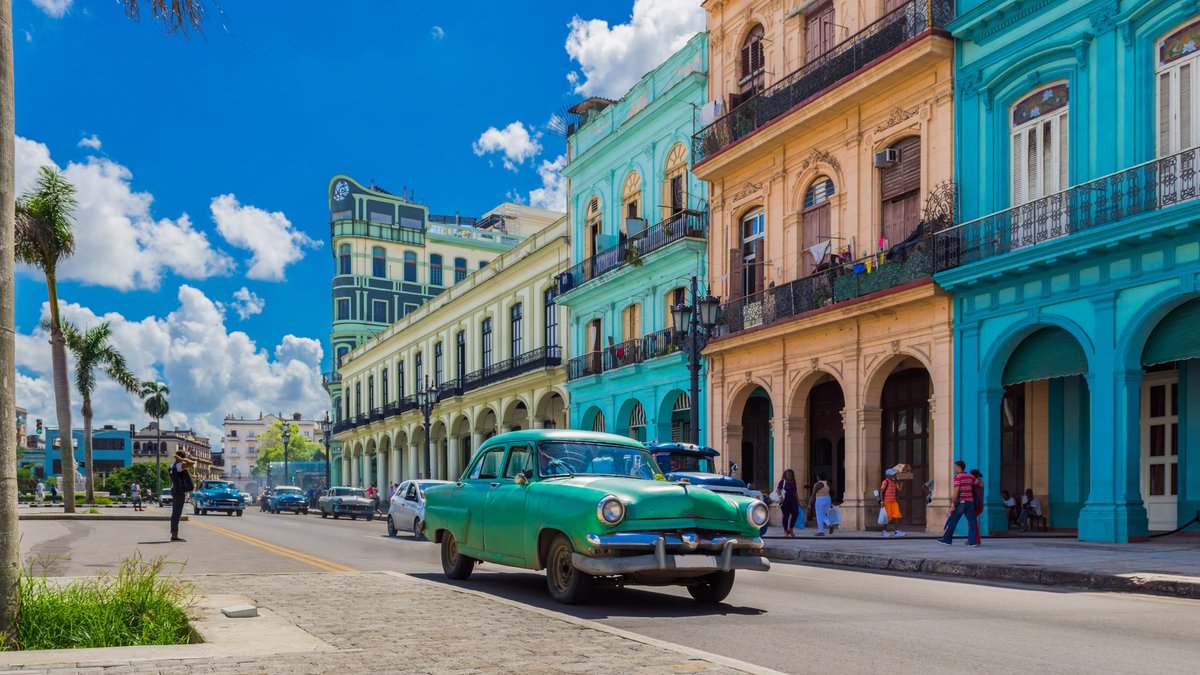
The U.S. Supreme Court has eased the way for people and companies to make claims over the confiscation of Cuban property when Fidel Castro seized power in 1959. In the case Havana Docks Corp. v. Royal Caribbean Cruises, Ltd., 608 U.S. ___ (2026), the high court revived a lawsuit filed by Havana Docks, a U.S. firm that once operated docking facilities in Havana. The action targeted four cruise operators that transported tourists to Cuba during the brief diplomatic reopening under President Obama, alleging that they used assets that Havana Docks asserts were confiscated.
The statute at issue is the Cuban Liberty and Democratic Solidarity (Libertad) Act of 1996, more commonly known as the Helms-Burton Act. This law establishes a cause of action for persons whose private property was expropriated by the Cuban government, allowing them to seek compensation from private entities that “traffic” in such taken property. It thus provides an avenue for plaintiffs to obtain redress for their damages from nongovernment parties that have made economic use of the confiscated property.
Under the Helms-Burton framework, “trafficking” encompasses any person who “purchases, leases, receives, possesses, obtains control of, manages, uses, or otherwise acquires or holds an interest in confiscated property,” as well as anyone who “causes, directs, participates in, or profits from, trafficking… by another person, or otherwise engages in trafficking… through another person, or who holds an interest in or profits from confiscated property,” according to 22 U.S.C. § 6023(13).
Trump Administration Lifts Helms-Burton Suspension
Despite the significant liability ostensibly created by the Helms-Burton Act, for twenty-three years, Title III of the act, which provided for the cause of action described above, was suspended by United States presidents of both major political parties in view of broader international implications. The suspension ended in 2019 when the Trump administration lifted it, permitting Helms-Burton claims to move forward. At the same time, President Trump imposed travel bans that halted the cruise vessels central to the Havana Docks dispute.
When damages are awarded for property taken many decades ago, the recipients are frequently the heirs of the original owners. Although the payment is typically a cash settlement rather than a return of the actual asset, the Internal Revenue Service treats such recoveries as taxable income, as the IRS taxes most lawsuit settlements.
From a tax perspective, an “involuntary conversion” occurs when property is destroyed, stolen, condemned, or otherwise disposed of under a threat of condemnation and the owner receives money or other consideration in return. The proceeds may stem from insurance payouts, condemnation awards, or legal settlements. The governing provisions are found in Section 1033 of the Internal Revenue Code.
Federal tax law generally treats these receipts as the proceeds from the disposition of the property, which can generate taxable gain depending on the taxpayer’s basis, much like any ordinary sale. Section 1033 permits a taxpayer who experiences an involuntary conversion to defer the gain by reinvesting in similar property, a mechanism comparable to a Section 1031 exchange but subject to its own set of timing rules and restrictions.
Tax Treatment of Property Confiscation Awards
The IRS tends to assume that litigation settlements are ordinary income. However, many successful Helms-Burton Act plaintiffs are likely to have good arguments that settlement proceeds should qualify for long-term capital gain treatment. After all, having property confiscated should mean that a later settlement is effectively paying you for your property. The language of the settlement agreement can bolster that position.
Read Also: Streamers Face Copyright Risks, Business Disruptions Under DMCA
For individuals, ordinary income is taxed at up to 37 percent, while capital gain can be taxed as low as 0 percent and as high as 23.8 percent. Apart from lower tax rates, capital gain can involve recouping basis, too. If you spent $1 million in costs (such as legal fees) that you have not deducted, that is basis that can be repaid without tax before you start reporting gain.
The tax consequences differ for business entities that bring Helms-Burton actions.
Legal Fee Deductions
Many claimants lack a substantial tax basis because of the decades that have elapsed since the 1959 confiscations. Nevertheless, most litigants retain contingent-fee counsel. When a recovery is realized, the IRS treats the claimant as receiving both the net award and the portion allocated to the contingent-fee attorney, prompting the need to claim a deduction for legal fees.
Income vs. Property Claims
Although Helms-Burton actions fundamentally address confiscated property, some cases focus on lost income rather than the value of the property itself. It is not uncommon for the IRS in various contexts to say that loss of income claims means that a resulting settlement or judgment is taxable as ordinary income. In some cases, though, an alleged income stream is used as a kind of proxy for the value of the items taken.
NCA Argyle Case Shows Capital Gain Treatment
In NCA Argyle LP v. Commissioner, T.C. Memo. 2020-56, the Internal Revenue Service and the taxpayer Newport Capital Advisors, LLC disputed the tax treatment of a $23 million settlement. The taxpayer argued that the amount represented capital gain derived from its interests in the dissolved joint ventures. The IRS contended that the payment reflected future fees the ventures would earn plus punitive damages, both of which are taxed as ordinary income.
The settlement agreement stated that NCA received all $23 million in exchange for its interests in the joint ventures. Although settlement agreement wording does not bind the IRS, the Tax Court relied heavily on the express allocation in the settlement agreement. The court agreed with the taxpayer that these were sale proceeds and capital gain.
Tax Deferral Under Section 1033
Section 1033 offers another possible tax advantage for damages stemming from Cuban confiscations. The provision allows a taxpayer to reinvest the realized gain into the repair or replacement of damaged or destroyed property, subject to specific time frames and requirements. While commonly applied in property-damage and construction-defect cases, the rule could also be invoked in Helms-Burton matters.

Leave a Reply